A premium card can give us more room for large purchases, but its limit may be fixed or flexible. Credit utilization means the share of available revolving credit we currently use. That share can affect how lenders view our credit use, so a larger limit does not make a balance harmless.
We can compare cards by their spending structure, travel rewards, lounge access, and annual fee. Some suit people who want a set borrowing limit. Others offer flexible spending power, while business and secured cards meet different needs. A high credit score may help, but it cannot promise approval or a specific limit.
We should compare the card’s likely spending structure and benefits against what we can afford to pay.
Key Takeaways
- A fixed credit line sets a stated borrowing ceiling.
- Flexible spending does not mean unlimited spending.
- Published minimums and reported limits are different facts.
- Annual credits matter only when they fit our habits.
- Income, debt, and credit history can affect approval.
- We should choose a payment we can manage each month.
What counts as a high credit limit?
A $10,000 line is a common starting point for calling a credit card high-limit, but personal and business benchmarks differ. In 2026, a personal-card limit above $15,000 or a small-business-card limit above $25,000 is usually considered high. The average U.S. credit-card limit across open accounts is around $30,000, though that average does not describe every cardholder.
A high limit can mean a line of $10,000 or more in general use. The highest published personal-card limits usually fall between $50,000 and $100,000. Those figures often require very good credit, high reported income, and an existing relationship with the issuer.
A high-limit label often starts at $10,000, while six-figure lines remain exceptional.
A rough ceiling for many applicants is 30%-40% of stated annual income, based on underwriting models. This is only a broad estimate, not an issuer formula. A $70,000 salary does not automatically lead to a $21,000 or $28,000 line.
FICO scores of 670 and above are often described as good to excellent. A stronger score may help, but income, debt, and account history still matter. Here are useful benchmarks for judging a reported credit limit.
- Personal cards: above $15,000 is usually high in 2026.
- Small-business cards: above $25,000 is usually high in 2026.
- Income: treat 30%-40% of annual income as a rough guide.
- Six-figure limits: view them as rare reports, not approval promises.
Treat any reported six-figure limit as an outlier, not a target an issuer must approve.
Fixed limits vs. flexible spending power
A fixed-limit card gives us a stated borrowing ceiling, while a flexible-spending card assesses purchases against our account profile. The difference shapes how much we can charge at one time. Flexible spending is not the same as unlimited spending.
Before a large purchase, we should know whether the card has a fixed line or a flexible spending model. The same card may also offer a separate way to carry eligible charges over time. Those features are not interchangeable.
How a fixed credit limit works
A fixed credit line is a revolving borrowing limit. Most fixed credit-card limits range from $200 to tens of thousands of dollars. When purchases post, they use part of the available credit; payments restore available credit after they post.
For example, a $10,000 line with $2,000 in posted purchases leaves $8,000 available. Pending charges may affect what we can spend before they post. The card’s account terms explain how the issuer handles those charges.
What “no preset spending limit” means
The American Express Platinum Card has no preset spending limit. Its flexible spending limit can change with our purchases, payment history, and credit history. A large charge may fit one account profile but not another.
Eligible Platinum charges may be added to a Pay Over Time balance, subject to the cardholder’s Pay Over Time limit. That separate limit controls how much eligible debt we may carry, not the card’s flexible spending power. Interest may apply to a carried balance.
Check whether a card has a fixed line or flexible spending before assuming it can cover a large purchase.
Best Premium Credit Cards with High Limits: Our Top Picks
For a premium card with a defined credit line, start by comparing the Sapphire cards and Venture X; for flexible spending, consider the Platinum. The best premium travel credit cards in 2026 are not simply the cards with the biggest reported limits. A high limit alone does not make a card the best fit.
We can compare rewards credit cards by their spending structure, benefits, and costs. These five cards offer different routes to travel value, and applicants still need excellent credit for some premium options. No pick promises approval or a specific line.
- Chase Sapphire Preferred: a strong fit for travel rewards and a defined line.
- Chase Sapphire Reserve: a high minimum and useful travel protections.
- Capital One Venture X: a premium travel setup with a lower annual cost than some rivals.
- American Express Platinum: flexible spending and airport lounge access.
- Citi Strata Premier: a card with reported starting limits worth comparing.
This list of premium credit cards suits different travel styles. The Preferred focuses on earning rewards for travel. The Reserve may suit readers who value a stated minimum and insurance benefits.
Venture X offers a premium travel option with a simple base reward rate. The Platinum is different because it has no preset spending limit. Citi Strata Premier is another option when we compare reported starting lines and travel rewards.
We should compare how each card handles travel, everyday spending, and the benefits we will use. A rewards card can look appealing while offering little value for our actual trips. Approval terms also vary by applicant.
Choose the card that fits both our spending structure and the benefits we expect to use.
Chase Sapphire Preferred for travel rewards
The Preferred’s typical starting line is at least $5,000, while user data places its average above $10,000. This Visa Signature card may suit us if we want travel rewards and a defined limit. The reported average is not a promised starting line.
We should weigh the card’s travel value against how we book trips. A card can earn points and still be a poor fit if its benefits go unused. Its hotel credit applies only to certain bookings.
Its starting line and reported limits
Visa Signature cards typically start with a credit limit of $5,000 or more. Credit Karma user data places the Preferred’s average limit above $10,000. That average is a guide from user accounts, not an offer every applicant receives.
Some cardholders have reported limits as high as $500,000 for the Preferred and Reserve. The figure comes from Quora remarks, so it is an anecdotal high across two Sapphire products. It is not a likely approval amount or a guarantee.
Who benefits most from its travel rewards
The Preferred can suit travelers who want points and a hotel benefit without choosing a card for luxury perks alone. Its Annual Chase Travel Hotel Credit is worth up to $100 toward eligible hotel stays booked through Chase Travel. We need to use that booking channel to get the credit.
Points and bonus points can add value when they match trips we already plan to take. A credit that changes our booking habits may not save us money. The card’s rewards also matter less if we rarely travel.
Consider the hotel credit only if we regularly book eligible stays through Chase Travel.
Chase Sapphire Reserve for a high minimum and protections
Reserve applicants must qualify for at least a $10,000 starting line because it is a Visa Infinite card. That requirement gives the card a clear floor, but it does not predict a much higher limit. The network minimum is $10,000.
Travel protections may also help us decide whether this card fits. We should look at the covered events and terms, not just the size of a credit line. The card’s points and benefits should match our plans.
The Visa Infinite starting requirement
Visa Infinite cards require a starting credit limit of $10,000 under the network’s terms. The Reserve meets that threshold, so applicants must qualify for at least that amount. The requirement does not mean every applicant will be approved.
A high-limit credit card application still depends on the issuer’s review. FICO scores of 720 or higher are generally expected for high-limit cards, while scores of 760 or higher are often linked with the highest tiers. These are broad expectations, not fixed approval rules.
Reported limits and insurance value
Cardholders have reported Reserve limits as high as $80,000 on myFICO Forums. The card often starts around $10,000-$15,000 and may grow above $50,000. These figures describe different outcomes, and account history and underwriting affect the result.
The Reserve includes trip delay and baggage delay coverage. It also offers rental-car coverage and trip cancellation or interruption insurance. These protections can matter when a trip goes wrong, but we should read the benefit terms before relying on them.
Treat the network minimum as an approval threshold, not a prediction that we will receive a much larger line.
Capital One Venture X for premium travel value
Venture X often opens with a five-figure line, with reports placing typical starting limits between $10,000 and $20,000. Some accounts may grow above $40,000. These reported ranges are estimates, not issuer guarantees.
The card can suit travelers who want a fixed line and rewards on routine purchases. Its base rate makes it simple to earn miles without sorting every purchase into a bonus category. A welcome offer can add value if its spending target fits our budget.
Typical opening limits and growth
Reports put Venture X opening limits at $10,000-$20,000, with some accounts growing above $40,000. A lender may offer less or more based on its review of the applicant. The figures should help us set expectations, not predict an approval.
We should also think about how much credit we need for planned costs. A larger line can help with a major trip or purchase, but it can also make it easier to take on debt. Payments still need to fit our budget.
How its travel rewards fit everyday spending
Venture X earns 2 miles per dollar on every purchase. Its 2026 welcome offer gives 75,000 bonus miles after $4,000 in purchases within the first three months from account opening. Offers can change, so the terms at application matter.
Everyday spending can build rewards between trips. We should not add extra purchases just to reach a bonus. The miles only help if we can use them for travel we would choose anyway.
Make sure the welcome-offer spending target fits purchases we would make anyway.
American Express Platinum and flexible spending
The Platinum can accommodate substantial spending for some cardholders, but it does not promise an unlimited line. American Express reviews purchases against each account’s profile. Flexible spending can change over time.
Some cardholders use the card for purchases of $30,000 or more. That does not mean every large charge will be approved. We should check spending power before relying on the card for a major bill.
How the flexible limit is assessed
The American Express Platinum Card has no preset spending limit. Its flexible spending limit can reflect purchase patterns, payment history, and credit history. Those factors may shift as the account changes.
That structure differs from a fixed credit line shown on many credit cards. The card can approve one large purchase and decline another. A past approval does not guarantee the next charge will go through.
The card earns 5 points per dollar on eligible flights and prepaid hotels. Those rewards can suit travelers who book those types of trips. We should check which purchases count as eligible before estimating the value.
Pay Over Time is a separate limit
Eligible charges may be added to a Pay Over Time balance up to the cardholder’s Pay Over Time limit. That limit sets how much eligible spending we can carry, not how much the card may approve overall. The two features serve different purposes.
Carrying an eligible balance can incur interest. Interest can reduce the value of points and statement credits, especially when a balance lasts for months. Paying the full statement balance helps avoid interest on charges not placed in Pay Over Time.
Check spending power before a major purchase and confirm whether the charge is eligible for Pay Over Time.
Which Bank of America cards have reported high limits?
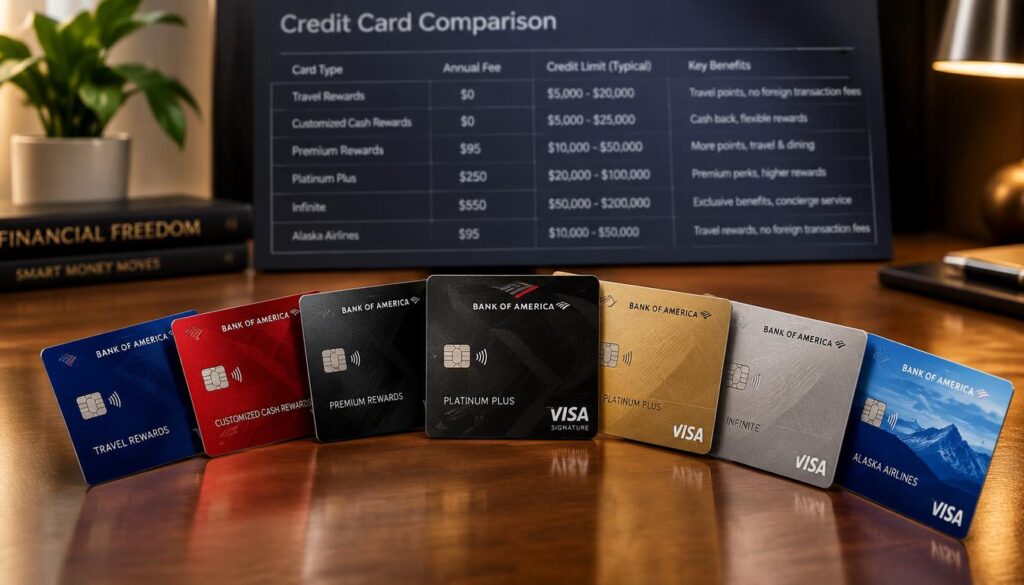
The Premium Rewards card has an indirect report of a $120,000 limit, while Customized Cash Rewards has cardholder reports of $95,000. Those figures are striking, but they are user reports rather than issuer promises. Reported limits do not show what a new applicant will receive.
Citi Strata Premier has a reported starting range of $10,000-$25,000 in 2026. That range gives us another point of comparison, though each applicant’s approval terms can differ. The table separates each figure from the kind of evidence behind it.
| Card | Reported or starting limit | Evidence type |
|---|---|---|
| Bank of America Premium Rewards | Up to $120,000 | Indirect forum comments |
| Bank of America Customized Cash Rewards | $95,000 | Cardholder reports |
| Citi Strata Premier | $10,000-$25,000 | Reported starting range |
The Premium Rewards figure comes from indirect forum comments. It is less direct evidence than a cardholder describing their own account. Even first-person reports cannot tell us the full terms behind an individual approval.
The $95,000 Customized Cash Rewards figure is also a reported outcome. Neither Bank of America card publishes these numbers as a guaranteed limit. An issuer may set a lower line for an applicant.
Treat both Bank of America figures as reported outcomes, not limits the issuer promises.
Which business cards can offer high limits?
Small-business cards can start higher than many personal cards, with some qualifying applicants receiving $20,000-$50,000. Chase Ink Business Preferred and American Express Business Gold are options for established small businesses. Qualifying businesses may receive more than $25,000.
A business card should fit the company’s cash flow, not just its spending needs. We should compare how a card handles repayment and which purchases earn rewards. A high line can still create trouble if income arrives late.
Cards for established small businesses
Chase Ink Business Preferred and American Express Business Gold often start at $20,000-$50,000 in 2026. Both often issue limits above $25,000 to qualifying small businesses. Those ranges are common reports, not a promise for every new account.
Business owners may need room for inventory, travel, or other costs before customer payments arrive. We should keep business and personal spending clear in our records. The right line depends on what the company can repay.
What to compare before applying
Ink Business Premier is another option, with cardholders reporting limits of $10,000 or more. It requires full monthly payment. The card earns 2% cash back on other purchases and 2.5% on purchases of $5,000 or more.
Before applying, we can check four parts of the offer and our business plan.
- Business cash flow: Can sales cover the card balance?
- Personal-credit review: Does the application include a personal credit check?
- Payment terms: Must we pay in full each month?
- Rewards fit: Do the rewards match our regular business expenses?
Choose a business line that the company can repay from its cash flow, not just one that can be approved.
Do luxury cards offer the biggest limits?
A luxury card’s price and perks do not tell us how large its credit line will be. High fees may buy lounge access, statement credits, or service, but they do not prove a high limit. Status is not a credit-line guarantee.
The search for the most powerful credit card in the world has no useful single answer. Prestige, perks, and spending capacity are different measures. We should compare the benefits with our own needs.
Mastercard Black Card and Gold Card costs and perks
The Mastercard Black Card has a $699 annual fee in 2026. Each authorized user costs $249 per year. The card includes more than 1,800 airport lounges, with unlimited visits for the cardholder and guests.
It also offers up to $200 in annual airline statement credits and up to $100 in annual dining statement credits. The Mastercard Gold Card costs $1,199 per year, plus $349 for each authorized user. Those prices do not reveal either card’s credit limit.
The Gold Card’s high cost may appeal to people who value its status or benefits. We should not assume the fee means the issuer will offer more spending power. Mastercard Gold Card membership is not a limit ranking.
What makes a credit card powerful?
A card can feel powerful because it offers a service we value, or because it supports a large purchase. Those are separate qualities. A card’s benefits do not show how much credit an issuer will extend.
There is no official ranking for the most powerful credit card in the world. The stated fees and benefits for these luxury cards do not establish a credit-limit ranking. We should judge each feature on its own.
Compare a luxury card by the benefits we will use, not by assuming its status guarantees exceptional spending power.
What determines a starting credit limit?
Issuers weigh income alongside credit scores, debts, utilization and debt-to-income ratio, rather than using salary alone. The 2009 Credit CARD Act requires an ability-to-pay assessment before an issuer opens a card or raises a limit. That rule does not create a formula that turns income into a credit line.
Income can help show that we can repay a balance, while existing debt can reduce room in our budget. A long relationship with an issuer may also help it understand how we use accounts. No single factor sets the limit.
Income, debt and existing accounts
In 2026, the highest limit tiers usually require reported income of $75,000 or more. This is a broad pattern, not a minimum income rule for every card. Income alone cannot predict a precise limit.
Issuers may review outstanding debts and our debt-to-income ratio, which compares debt payments with income. Existing accounts can show how we manage credit. A relationship with the issuer may help, but it cannot replace the full review.
Credit history and utilization
Premium high-limit cards generally expect FICO scores of 720 or higher. Scores of 760 or higher are often linked with the highest tiers. Issuers may also favor five or more years of credit history and no late payments in the previous 24 months.
Credit utilization is the share of available revolving credit currently used. Utilization above about 30% can cause credit scores to decline in 2026. Keeping balances lower may help our profile, though it does not ensure a larger limit.
| Factor | Useful benchmark | Why it matters |
|---|---|---|
| FICO score | 720+; 760+ for highest tiers | Approval profile |
| Credit history | 5+ years | Account maturity |
| Payment record | No late payments in prior 24 months | Repayment history |
| Utilization | Above about 30% may hurt scores | Share of available credit used |
The law requires an ability-to-pay assessment, but no formula converts salary alone into a limit. Debts, score, and utilization can change how an issuer views the same income.
Keep balances manageable and check the full credit profile before applying.
How can we build toward a higher limit?
Six months of responsible use can be a reasonable point to ask an issuer whether an increase request is available. On-time payments and low balances can support a stronger account history. An increase is never automatic.
We should use the card for expenses we can repay, rather than spending more to impress the issuer. A clear payment record gives the account a useful track record. A request may still be denied.
Habits that support a future increase
Paying on time matters most. We can also keep revolving balances low and use existing credit responsibly. Carrying a balance does not prove we need more credit, and interest can add needless cost.
Capital One QuicksilverOne may be considered for an increase after six months of on-time payments. That review does not mean the issuer will approve an increase. Each issuer sets its own review process and account rules.
When and how to request more credit
Some issuers allow a credit-limit increase request after about six months of responsible use. We can use the issuer’s normal channel when our account is eligible. The issuer may ask about income during the request.
Consumers do not have to give an issuer income information unless applying for a new card or requesting a credit-limit increase in 2026. We can prepare by checking our records first. These steps help us make a careful request.
- Review our credit reports for errors.
- Pay every bill on time.
- Lower revolving balances before asking.
- Request an increase through the issuer’s normal channel when eligible.
Request only a limit we can manage, and never treat an increase as guaranteed.
Which premium card is best for airport lounge access?
For broad airport-lounge access, American Express Platinum is the strongest fit among these options. It provides access to Centurion Lounges and is a leading consumer lounge card in 2026. Choose the network we can use on our routes.
Capital One Venture X and Chase Sapphire Reserve are also premium travel cards with lounge access. The best card depends on the airports we use and the guest rules we need. Enrollment may be required.
Lounge access for frequent travelers
American Express Platinum can suit travelers who want Centurion Lounge access. Capital One Venture X may fit those seeking a premium travel card with airport lounge access. Chase Sapphire Reserve includes Priority Pass Select and Chase Sapphire Lounge access.
At Sapphire Lounges, the Reserve permits two guests in 2026. That guest allowance can help when we travel with family or a companion. Lounge access still depends on the card’s current rules.
Choosing among issuer lounge networks
The table shows the main lounge fit for each card. We should check which network serves the airports on our usual routes. A lounge benefit has less value if we rarely pass through a participating location.
| Card | Lounge access | Best fit |
|---|---|---|
| American Express Platinum | Centurion Lounges | Travelers prioritizing that network |
| Capital One Venture X | Airport lounge access | Travelers wanting a premium travel card |
| Chase Sapphire Reserve | Priority Pass Select and Sapphire Lounges; two guests at Sapphire Lounges | Travelers who value Chase’s networks |
Access rules, enrollment, and guest policies can differ between networks. Some benefits may require us to enroll before visiting. Rules can also affect whether guests enter at no extra cost.
Check each card’s current enrollment and guest rules against the airports we actually use.
How should we weigh annual fees against benefits?
A fee is worthwhile only when the benefits we will actually use outweigh its annual cost. We can compare the annual fee with credits tied to travel or other planned spending. Unused credits do not reduce what we pay.
Some credits require enrollment, specific merchants, or certain booking dates. Rewards may also have different values when redeemed for travel, gift cards, or statement credits. A high points balance does not always equal the same cash value.
| Card | Annual fee | Benefit to compare against the fee |
|---|---|---|
| Chase Sapphire Preferred | $95 | Up to $100 hotel credit through Chase Travel |
| Chase Sapphire Reserve | $550 | Up to $300 annual travel credit |
| Capital One Venture X | $395 | Up to $300 annual Capital One Travel credit |
| American Express Platinum | $895 | More than $3,000 in annual statement credits |
The Platinum’s statement credits add up to more than $3,000 in annual value on paper. We should count only credits we can use without changing our normal spending. Some may have merchant, timing, or enrollment limits.
Travel rewards can also change in value depending on how we redeem them. A transfer to a travel partner, a gift card, and a statement credit may not return equal value. We should use a realistic estimate.
Add up the credits we can realistically use in a year before deciding to pay an annual fee.
What if we do not qualify for a premium high-limit card?
If a premium card is out of reach today, a secured card can provide a more controlled way to build credit. A deposit usually sets the card’s limit, so we should choose an amount that fits our budget. A $25,000 secured line requires a sufficiently large deposit.
First Tech Federal Credit Union Platinum Secured Mastercard offers limits as high as $25,000 when the cardholder provides a large enough deposit in 2026. Many secured cards require a deposit around $200, which serves as the credit line. The amount depends on the card and deposit.
An unsecured card may be another way to build payment history. Capital One QuicksilverOne is an option for limited-to-fair credit and earns 1.5% cash back. We should compare its terms with our budget before applying.
We can choose among three practical paths:
- Consider a secured card and choose a deposit our budget can support.
- Build payment history with an accessible unsecured card.
- Wait, review credit reports, and reduce debt before applying again.
A secured limit is tied to the deposit. Reaching $25,000 means setting aside a sufficiently large sum, not simply requesting a higher line. That deposit may be unavailable for other needs while it backs the account.
Choose a secured deposit only when we can spare that money without risking essential bills.
Choose a deposit and monthly payment that will not strain essential expenses.
Conclusion
The right premium card is the one whose spending structure, approval prospects and usable benefits fit our finances. A Sapphire card or Venture X offers a stated credit line, while American Express Platinum uses flexible spending rather than a preset limit. Neither structure is automatically better.
Before applying, we should check our credit profile and estimate the value of benefits we will actually use. That simple check can help us avoid paying for perks that do not fit our travel or spending habits.
Before applying, review our credit reports and write down the annual fee and benefits we can realistically use.