In June 2026, about 16% of credit card applications were rejected. The right card depends on what we spend on most and whether we want rewards, a lower introductory rate, or a way to build credit.
APR is the annualized interest rate a card issuer charges on a balance carried from month to month, excluding fees. We can compare travel rewards, cash back, introductory APR offers, and cards for building credit by asking how each fits our real needs.
Our spending patterns matter, as does our ability to pay the balance. Rewards can help, but only when we can use them without taking on costly debt or managing rules that do not suit us.
Key Takeaways
- Match rewards to the purchases we already make.
- Compare any annual fee with benefits we expect to use.
- Paying in full can matter more than earning rewards.
- Introductory APR offers end, so plan for the regular rate.
- Credit-building cards can help with steady, on-time payments.
A card’s value comes from benefits we will actually use, after we account for its fee and the way we pay our balance.
Which Top Credit Cards Fit Common Goals?
For a broadly useful travel-rewards starting point, the Chase Sapphire Preferred pairs a 75,000-point offer with a $95 annual fee. That makes it a practical starting point for people who can use travel points and meet the offer’s spending rule.
Our best credit card choice depends on spending fit, cost, and how we handle balances. These top credit cards cover travel, simple cash rewards, a lower introductory rate, and fair or limited credit history.
Which card fits travel, cash back, or a lower rate?
| Goal | Card | Welcome offer | Annual fee |
|---|---|---|---|
| Flexible travel rewards | Chase Sapphire Preferred | 75,000 points after $5,000 in purchases in the first 3 months | $95 |
| Simple cash rewards | Wells Fargo Active Cash | $100 after $500 in purchases in the first 3 months | No annual fee |
| Long purchase or transfer APR window | Wells Fargo Reflect | No welcome offer stated | No annual fee |
| Fair or limited credit history | Capital One Platinum | No welcome offer stated | Check current terms |
How can we compare welcome offers without chasing a bonus?
Welcome offers commonly require eligible purchases worth a stated amount within a set period. The Chase Sapphire Preferred offer requires $5,000 in purchases during its first three months.
- Spending fit: choose a rewards credit card that matches everyday purchases we already make.
- Annual fee: weigh the fee against benefits we can use.
- Payment plan: know if we can pay in full or clear a transferred balance.
A welcome offer is useful only when its spending requirement fits purchases we already planned to make.
The “top credit cards for 2025” query refers to a past-year snapshot, not a promise of current terms. Before applying, check that the spending requirement fits purchases we already planned to make.
Which Points Cards Work Best for Travel?
The Chase Sapphire Preferred is a practical travel-points pick for travelers who want a $95 annual fee and elevated earning through Chase Travel. It fits a lower-fee entry point for flexible travel rewards.
Points earn different values based on how we redeem them. The best points credit card for travel depends on where we book and how we plan to use rewards.
| Card | Travel portal earning | Direct travel earning | Annual fee |
|---|---|---|---|
| Chase Sapphire Preferred | 5x through Chase Travel | 2x on other travel | $95 |
| Chase Sapphire Reserve | 8x through Chase Travel | 4x on flights and hotels booked directly | $795 |
| Citi Strata Premier | 10 points per dollar on hotels, car rentals, and attractions through Citi Travel | 3 points per dollar on air travel and other listed categories | Check current terms |
How do the Chase Sapphire cards earn on travel?
The Sapphire Preferred card earns 5x points on Chase Travel purchases and 2x points on other travel purchases. Chase Sapphire Reserve earns 8x through Chase Travel and 4x on flights and hotels booked directly.
Reserve suits travelers who value higher travel earning and accept its higher fee. Preferred suits people who want Chase Sapphire points with a lower annual cost.
When does the Citi Strata Premier fit a travel plan?
Citi Strata Premier earns 10 points per dollar on hotels, car rentals, and attractions booked through Citi Travel. It also earns 3 points per dollar on air travel, other hotel purchases, restaurants, supermarkets, gas, and EV charging stations.
Citi’s wide categories can suit mixed spending, though the portal rate has a booking condition. Points are not automatically equal in value, so compare our direct bookings with portal purchases before choosing an earning structure.
Which Premium Travel Cards Earn on Flights and Hotels?
The Venture X is the lower-fee option of these two, while the Platinum Card rewards a narrower set of flight and prepaid-hotel bookings at 5 points per dollar. The booking rules matter as much as the headline rate.
Venture X charges $395 a year, compared with $895 for the American Express Platinum Card. Venture X earns 10 miles per dollar on hotels and rental cars through Capital One Travel, plus 5 miles on flights and vacation rentals booked there.
It earns 2 miles per dollar on other purchases. The American Express Platinum Card earns 5 Membership Rewards points per dollar on eligible flights booked directly with airlines or through American Express Travel.
The Platinum flight rate applies to up to $500,000 in purchases per calendar year. It also applies to prepaid hotel bookings through American Express Travel.
The Platinum offer may reach 175,000 points after $12,000 in eligible purchases during the first six months. Offers vary by applicant, so a large bonus is not assured.
Some travelers value lounge access, but we should check current terms before counting it as a benefit. Neither a bonus nor a premium card justifies spending on purchases we would not otherwise make.
Choose a premium card only when its rewards and usable benefits can plausibly outweigh its annual fee.
Is Capital One Venture Rewards a Good Simple-Miles Card?
Capital One Venture Rewards keeps everyday earning simple at 2 miles per dollar, with a higher rate for eligible stays and rentals booked through Capital One Travel. The steady everyday rate suits people who prefer fewer spending categories.
The card earns 5 miles per dollar on hotels, vacation rentals, and rental cars booked through Capital One Travel. It earns 2 miles per dollar on every other purchase and has a $95 annual fee.
The current offer includes 75,000 miles after $4,000 in purchases during the first three months, plus a $300 Capital One Travel stays credit. Offer terms can change.
The portal rate can help when we already plan to book there. Compare the total booking price with other options before choosing a portal just to earn more miles.
For a Capital One Venture card, the miles’ value depends on the redemption we choose, not just the number earned. A large balance may not help if its rewards do not fit our travel plans.
People comparing One Venture Rewards and other Venture Rewards credit cards should focus on booking habits and likely redemptions. The per-dollar-spent rate is only one part of the value.
Which No-Fee Cards Earn Cash Back on Most Purchases?
For broad spending without an annual fee, both Citi Double Cash and Wells Fargo Active Cash earn 2% cash back or cash rewards. The timing differs between their two reward structures.
Citi Double Cash pays its second 1% when we pay for purchases. Wells Fargo Active Cash earns unlimited 2% cash rewards on purchases, with no annual fee.
| Card | Earning structure | Annual fee | Extra feature |
|---|---|---|---|
| Citi Double Cash | 1% when purchases are made, then 1% when paid | No annual fee | 0% for 18 months on balance transfers |
| Wells Fargo Active Cash | Unlimited 2% cash rewards on purchases | No annual fee | $100 bonus after $500 in purchases in the first 3 months |
The Active Cash offer is a $100 bonus after $500 in purchases during the first three months. The cash-back terms can suit people who do not want to track category changes.
- Eligible purchases: check which spending counts for rewards.
- Payment timing: understand when each part of the reward posts.
- Extra offer: compare any bonus or introductory rate with our needs.
We can read more about cash-back cards for different spending styles before choosing between broad and category-based rewards.
Pay the statement on time so the reward structure does not distract from the cost of carrying a balance.
Which Card Fits Grocery and Everyday Household Spending?
Blue Cash Everyday gives households grocery, gas-station, and eligible U.S. online retail categories without an annual fee. Its three categories can fit spending beyond the supermarket.
Blue Cash Everyday earns 3% at U.S. supermarkets, U.S. gas stations, and on U.S. online retail purchases. Each category has a $6,000 yearly cap, then earns 1%.
Its offer may reach $200 after $2,000 in purchases during the first six months. Offers vary by applicant, so we should not count on the maximum.
Blue Cash Preferred earns 6% at U.S. supermarkets on up to $6,000 per year in eligible purchases, then 1%. It also earns 6% on select U.S. streaming subscriptions.
Preferred earns 3% at eligible U.S. gas stations and on transit, plus 1% on other purchases. Its annual fee is $0 for the first year, then $95.
The Preferred offer may reach $300 after $3,000 in purchases during the first six months, with offers varying by applicant. Estimate annual eligible supermarket spending and account for the Preferred card’s fee after year one before deciding.
Which Cards Reward Dining, Entertainment, and Streaming?
Capital One Savor is the no-annual-fee cash-back option for dining, entertainment, popular streaming, and grocery-store purchases. Its rewards come as cash back, not points.
Savor earns 3% in those four categories, 8% on Capital One Entertainment purchases, and 5% on eligible travel through Capital One Travel. Other purchases earn 1%.
Savor offers $200 after $500 in purchases during the first three months. The offer has a set spending rule, and its no-annual-fee structure can suit category spenders.
The American Express Gold Card earns 4 Membership Rewards points per dollar at restaurants worldwide, up to $50,000 per calendar year, then 1 point. U.S. supermarkets earn 4 points per dollar up to $25,000 yearly, then 1 point.
The Gold Card has a $325 annual fee. Its offer may reach 100,000 points after $8,000 in eligible purchases during the first six months, though offers vary by applicant.
Cash back and Membership Rewards points are not directly comparable without considering redemption. Choose points over cash back only when we have a realistic plan to redeem them for value.
Is a Rotating-Category Cash-Back Card Worth the Effort?
Discover it Cash Back can earn 5% in selected categories, but only on up to $1,500 in quarterly purchases after activation. The categories change, so the rate takes attention.
Purchases above the quarterly cap and other purchases earn 1%. The card has no annual fee, but we must activate each quarter to get the rotating rate.
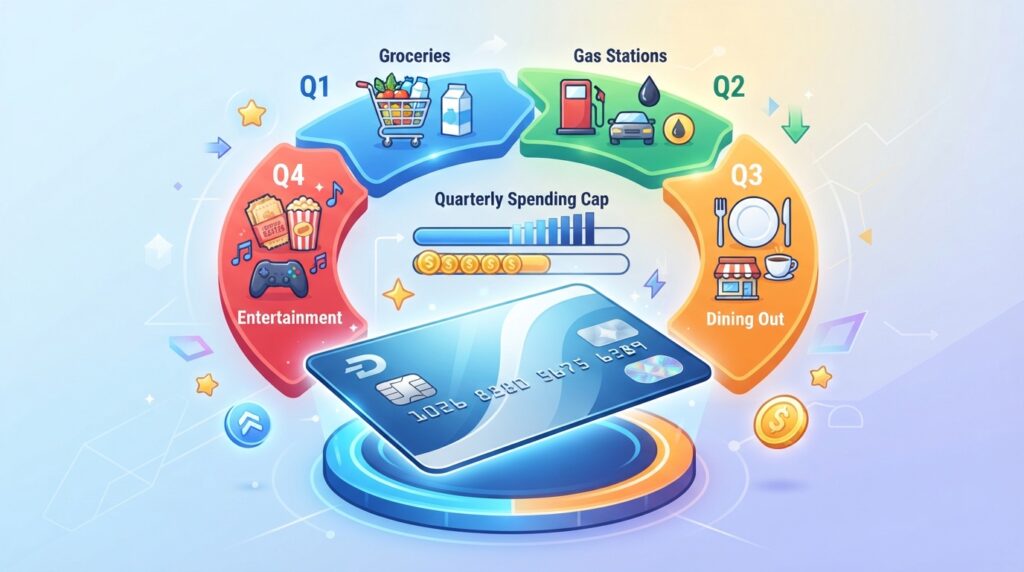
Not every purchase in a broad category will qualify. Check the current category list and its purchase rules before relying on a 5% rate.
For example, a household may use a quarter’s category for planned spending, then reach the cap before the quarter ends. Activate the categories each quarter and track spending against the cap.
Which Cards Can Help Pay Down a Balance Transfer?
Wells Fargo Reflect and Citi Diamond Preferred each offer a 21-month 0% balance-transfer period, while BankAmericard offers 21 billing cycles for eligible transfers. Timing can change the fit.
BankAmericard transfers must be made within the first 60 days. The regular variable APR applies after each introductory period ends.
How do the Wells Fargo and Citi offers compare?
| Card | Balance-transfer intro period | Transfer timing or eligibility | Post-intro APR |
|---|---|---|---|
| Wells Fargo Reflect | 0% for 21 months | Qualifying balance transfers | 17.74%, 24.24%, or 28.49% variable |
| Citi Diamond Preferred | 0% for 21 months | Qualifying balance transfers | 16.74%-27.49% variable |
| BankAmericard | 0% for 21 billing cycles | Transfer within first 60 days | 15.24%-26.24% variable |
Wells Fargo Reflect also offers 0% on purchases for 21 months from account opening. Each card has no annual fee.
What should we check before moving a balance?
- Confirm the balance and account qualify for a transfer.
- Calculate a monthly payment that can reduce the balance in time.
- Avoid new purchases on the transfer card while paying down debt.
Citi’s purchase promotion lasts 12 months, while its transfer period lasts 21 months. Set a payoff schedule that clears as much of the transferred balance as possible before the introductory rate ends.
Which Cards Offer 0% Intro APR on Purchases?
For purchases, BankAmericard offers 0% for 21 billing cycles, while the Quicksilver offer provides 15 months at 0%. BankAmericard lasts longer for eligible purchase balances.
Both rates are temporary, and the regular variable APR applies after the offer ends. BankAmericard also covers qualifying balance transfers made in the first 60 days.
BankAmericard has no annual fee and then charges a variable APR of 15.24%-26.24%. The Quicksilver purchase offer lasts 15 months.
A purchase offer can spread the cost of a planned expense, but it does not remove the debt. Plan to repay the purchase balance before the introductory period ends rather than relying on the promotional rate indefinitely.
Which No-Annual-Fee Cards Cover Several Spending Categories?
Chase Freedom Unlimited combines a Chase Travel bonus with dining and drugstore cash back, while Wells Fargo Autograph covers several everyday categories at 3X points. The rewards are different currencies.
Freedom Unlimited earns 5% on travel purchased through Chase Travel, 3% on dining and drugstore purchases, and 1.5% elsewhere. It has no annual fee.
Wells Fargo Autograph earns 3X points at restaurants, on travel, at gas stations, on transit, on popular streaming services, and on phone plans.
Freedom Unlimited returns cash back, while Autograph earns points. The Chase Travel rate applies only to portal bookings, so it differs from the card’s everyday categories.
People comparing Chase Freedom with Freedom Unlimited should look at where their regular purchases fall. Match the bonus categories against a recent month of spending rather than choosing by the longest list.
Which Cards Can Help Build or Rebuild Credit?
Capital One Platinum requires no security deposit and is available to applicants with fair credit or limited credit history. It is an unsecured option for eligible applicants.
A credit-line increase or card upgrade is possible, not guaranteed. Capital One may review Platinum accounts for a credit-line increase after six months.
What can applicants with fair or limited credit consider?
Capital One Platinum can suit someone who wants a card without putting down a security deposit. Approval still depends on the application and issuer review.
How do secured cards and starter cards differ?
Discover it Secured Cash Back requires a security deposit. It earns 5% in activated rotating categories on up to $1,500 per quarter, then 1% elsewhere.
Discover matches the cash back earned in the first year at that year’s end. Chase Freedom Rise offers a $25 statement credit for signing up for automatic payments within the first three months.
After 12 months of responsible use, Chase evaluates the account for a possible upgrade to Chase Freedom Unlimited. Start with these habits:
- Pay every bill on time.
- Keep balances manageable compared with the credit limit.
- Review the account terms and any deposit requirement.
Use a new account consistently and pay on time before expecting a review or possible upgrade.
Which Student Card Offers Useful Rewards Without an Annual Fee?
Capital One Savor Student offers several 3% categories without an annual fee, plus higher rates on Capital One Entertainment and eligible Capital One Travel bookings. The category mix includes common student spending.
The card earns 3% on dining, entertainment, popular streaming, and grocery-store purchases. It earns 8% on Capital One Entertainment purchases and 5% on eligible travel booked through Capital One Travel.
Other purchases earn 1%. The card has no annual fee and offers $50 after $100 in purchases during the first three months.
The welcome offer depends on eligible spending. A student should make sure the required purchases fit the budget instead of buying extra items for a bonus.
Paying the monthly bill on time matters more than the reward rate. A starter card is only useful if the monthly bill fits the student’s budget and can be paid on time.
Do Issuer Size and Approval Odds Tell Us Which Card to Choose?
A large issuer can have extensive card offerings, but its market size does not tell us whether a particular applicant will be approved. Approval remains personal.
About 16% of credit card applications were rejected in June 2026. That broad figure does not predict any one person’s result.
| Issuer | 2024 purchase volume | 2023 share of U.S. outstanding balances |
|---|---|---|
| Chase | $1,344 billion | 16.92% |
| American Express | $1,168 billion | 12.01% |
| Citi | $616 billion | 11.21% |
| Capital One | $610 billion | 10.84% |
| Bank of America | $502 billion | 9.39% |
Chase had the highest purchase volume among these five issuers in 2024. That does not make every Chase card the best credit choice for every person.
- Review our credit history before applying.
- Confirm the card’s eligibility rules and terms.
- Apply only when the card fits our budget.
Issuer volume and market share do not establish any applicant’s approval odds.
Large banks may offer many products, but a big portfolio cannot make a card match our needs. Treat approval as uncertain and avoid submitting applications for cards that do not fit our credit profile.
How Should We Compare Annual Fees and Rewards Value?
Start by estimating the rewards we would actually earn on normal spending, then compare that value with the annual fee and benefits we would use. Real spending comes first.
A reward rate is not the same as the value we receive when redeeming points or miles. A card can earn quickly but still offer poor value for our redemption plans.
How can we compare a fee with rewards we will use?
Estimate rewards on purchases we already make, then count only benefits we expect to use. An annual fee makes sense only if those rewards and benefits can offset its cost.
When do points or miles beat cash back?
Points or miles may work better when our planned redemptions give them strong value. Cash back is easier to compare because its value is clear at the time we earn it.
| Comparison step | What to check | Decision test |
|---|---|---|
| Annual fee | Fee and usable benefits | Will likely value cover the fee? |
| Everyday earning | Rewards on usual purchases | Does the rate fit our spending? |
| Bonus categories | Category rules and limits | Do we spend enough there? |
| Redemption value | Cash, points, or miles used | Can we use the reward well? |
A general benchmark is around 2% cash back or 2 points or miles per dollar on everyday purchases. Bonus categories commonly earn around 3x-6x.
Those figures help compare earning rates, but they do not mean points equal cash. APR describes interest on a carried balance and excludes annual fees and other fees.
Choose the card whose likely net value and payment terms fit our habits, not the one with the largest headline reward rate.
Conclusion
The strongest choice for us is the card that fits our spending and remains manageable after its introductory offer ends. Our payment habits matter as much as rewards.
Before applying, narrow the choice to one or two cards that match our regular purchases and credit needs. Check the annual fee, promotional end date, and payment terms that apply to each account.
A rewards credit card can return value, but carrying a balance may outweigh those gains. Review the issuer’s current terms and eligibility requirements for the card that best matches our needs before submitting an application.